By Sang Lee — Founder and Editor of AssetCalculus | Published by AssetCalculus
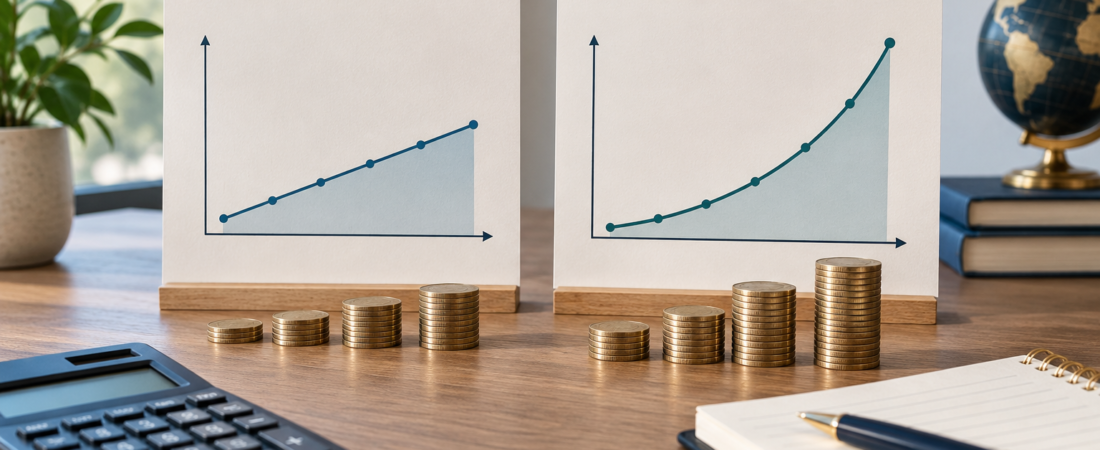
Quick answer: Simple interest is calculated only on the original principal. Compound interest is calculated on the principal plus previously earned interest. Over a short period the difference may be small, but over many years compounding can create a much larger ending balance.
Simple Interest Explained
Simple interest pays or charges the same dollar amount each period when the principal, rate, and time remain unchanged. The standard formula is:
Interest = Principal × Annual Rate × Time
If $10,000 earns 5% simple interest for three years:
$10,000 × 0.05 × 3 = $1,500
The ending balance is $11,500. The account earns $500 each year because interest is never added to the base used for the next year’s calculation.
Compound Interest Explained
Compound interest adds earned interest to the balance. Future interest is then calculated on that larger amount. Investor.gov describes this as earning interest on principal and on accumulated interest.
For a single initial deposit with no additional contributions, the formula is:
Ending balance = P(1 + r/n)nt
- P = starting principal
- r = annual interest rate as a decimal
- n = compounding periods per year
- t = number of years
The Same $10,000 Example
If $10,000 earns 5% compounded annually for three years, the balance becomes:
$10,000 × (1.05)3 = $11,576.25
The compound-interest balance is $76.25 higher than the simple-interest balance after only three years. The gap grows with more time because each round of interest can earn additional interest.
| Year | Simple-interest balance | Compound-interest balance |
|---|---|---|
| 0 | $10,000.00 | $10,000.00 |
| 1 | $10,500.00 | $10,500.00 |
| 2 | $11,000.00 | $11,025.00 |
| 3 | $11,500.00 | $11,576.25 |
| 10 | $15,000.00 | $16,288.95 |
| 20 | $20,000.00 | $26,532.98 |
Why Compounding Frequency Matters
Interest may compound annually, quarterly, monthly, or daily. With the same stated annual rate, more frequent compounding generally produces a slightly higher effective annual yield because interest is added to the balance sooner.
That does not mean frequency is the only number to compare. For deposit accounts, APY already reflects compounding over one year and is usually more useful than comparing the stated interest rate alone. Fees, minimum balances, withdrawal rules, and whether the rate can change also matter.
Where You May See Each Method
- Simple interest: Some short-term loans, certain installment arrangements, and educational examples.
- Compound interest: Savings accounts, certificates of deposit, many investment-growth projections, and balances where returns remain invested.
- Loans: Real loan calculations may use amortization, daily accrual, fees, or other terms. Read the contract rather than assuming a loan uses the classroom simple-interest formula.
Compounding Can Help or Hurt
For a saver or investor, compounding can accelerate growth when earnings stay invested. For a borrower, compounding can increase the amount owed when unpaid interest is added to the balance. The mathematical mechanism is the same; whether it helps depends on which side of the account you are on.
Inflation Still Matters
A growing balance does not guarantee an equal increase in purchasing power. The Bureau of Labor Statistics uses the Consumer Price Index to measure changes in prices paid by consumers. If an account compounds at 4% while inflation is 3%, the real gain is much smaller than the 4% headline rate.
Use the Inflation-Adjusted Return Calculator when you want to compare an investment return with inflation.
Try the AssetCalculus Calculator
The Compound Interest Calculator lets you enter a starting balance, contribution amount, rate, time period, and compounding frequency. You can also read What Is Compound Interest? for another plain-English explanation of how reinvested earnings build over time.
Frequently Asked Questions
Which is better, simple or compound interest?
For earning money at the same rate, compound interest produces more over time. For borrowing, simple interest may cost less, but actual loan terms and fees determine the result.
Is APY simple or compound interest?
APY incorporates the effect of compounding over a year, which makes it useful for comparing deposit products on a more consistent basis.
Does compound interest guarantee investment growth?
No. Calculator projections assume a rate. Market investments can gain or lose value, and future returns are not guaranteed.
Bottom Line
Simple interest grows in a straight line because it is calculated only on the original principal. Compound interest grows on an expanding base because accumulated earnings become part of the next calculation. Rate, time, contributions, and compounding frequency determine how large the difference becomes.
Educational note: This article is for general educational and informational purposes only. It does not constitute individualized financial, investment, tax, or legal advice.